Showing posts with label robbing depositors with NIRP. Show all posts

Sunday, August 28, 2016

Negative Interest Rates: A Tax in Sheep’s Clothing … A negative interest rate is just a tax on the banks’ reserves. The tax has to be borne by someone: The banks can choose not to pass it on and just have lower after-tax profits. This will depress the share price of banks and weaken their balance sheets by having lower equity values.

 Thoughts from around the internet...everyone sees what cashless and NIRP really mean - CONTROL AND THEFT OF WEALTH.

-------------

Giving a small group of individuals the power to decide on the value and volume of money is a ludicrous concept from any standpoint. But the problem is abetted by the mainstream narrative that never discusses the underlying lack of logic.

 The mechanism of central banking is purposeful ruin. The end-result of this ruin is global governance. In the short-term this goal is disguised by an academic patina. But the long-term goal, an increasingly apparent one, is a brutal restructuring of the lives of seven billion people to benefit a handful of elite controllers.

 Negative rates should be integral part of central bank policy options … Central banks should make negative interest rates a fully integrated part of monetary policy in order to respond effectively to future recessions, according to an academic paper presented on Friday to some of the world’s top central bankers.  “It is only a matter of time before another cyclical downturn calls for aggressive negative nominal interest rate policy actions,” concludes Marvin Goodfriend - what a deceitful name, a professor of economics at Carnegie Mellon University and a former policy adviser at the Richmond Federal Reserve bank.  – Reuters (this man is a devil hiding under a cloak of academia and, BTW, what future recessions? we've been in the greatest recession for over 8 years and counting. This is why the front men for the machine of evil use pugs like this in jobs that pay nearly half a million dollars a year in salaries, because they sing the song of new world order and everyone trusts them because they have..."credentials.")

The problem with real money, banks can't make any money out of it every time is changes hands.
Thank god for counterfeit money, which is just one's and zeros stored on a computer somewhere.
Central Banks can move it around, create it, delete it and there's no record of it, that's why the Pentagram has "lost" over 9 Trillion Dollars, but it's pretty hard to loose something that never actually existed in the first place except inside a computer.

 - If they were serious about reducing crime, etc., they wouldn't allow big banks (eg, HSBC) to launder illegal monies for countries and drug cartels.
 - If they were serious about reducing income tax evasion, they wouldn't allow big corps (eg, Apple) to offshore their profits.
 - If they were serious about reducing corruption, they wouldn't allow big money in politics (eg, Citizens United ruling). Clinton is a poster-child for corruption, but I doubt she's ever received an envelope stuffed with $100 bills.
As most here realize, this is all about forcing the 99% into digital currency so they can be more easily controlled thru neg rates. Problem is, how do we get the masses to wake up to this grim future? I don't have the link handy, but Grep Ip of the WSJ recently wrote a piece praising more of the same from Rogoff about the evils of cash. All this is doing is giving the govt cover from "deep-thinking academic experts" to enact these draconian yet idiotic policies.

 This is very scary mainly because I see no resistance to the trend. One day I will wake up and cash will be gone and along with it all individual freedom ( whatever is left of it today.) 

 Beware the Money Changers.

the result of a constriction of credit and money, abject poverty for a nation


Monday, August 22, 2016

Every week in Europe, another MAJOR bank institutes negative interest rates for its depositors NIRP...

Deposits at Bank of Ireland are soon to face charges in the form of negative interest rates after it emerged on Friday that the bank is set to become the first Irish bank to charge customers for placing their cash on deposit with the bank. Yet another Central Bank of yet another country decides to help crash the economy and force savers into the dangerous waters of the stock market, which itself is about to crash to levels of historical firsts.
Bank-of-Ireland-007
No way out, except in Gold and Silver
This radical move was expected as the European Central Bank began charging large corporates and financial institutions 0.4% in March for depositing cash with them overnight.

Bank of Ireland is set to charge large companies for their deposits from October. The bank said it is to charge companies for company deposits worth over €10 million.
The bank was not clear regarding what the new negative interest rate will be but it is believed that a negative interest rate of 0.1 per cent will initially be charged to such deposits by Ireland’s biggest bank.

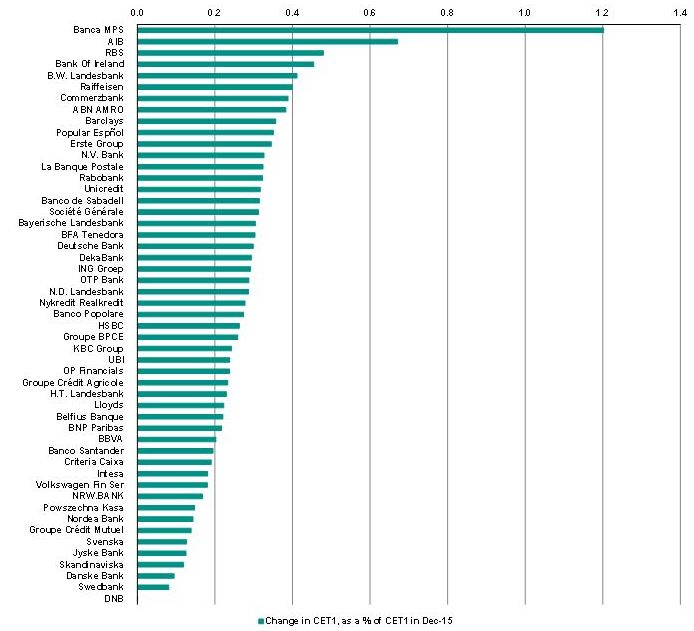
BOI recently failed the EU stress tests and is seen as one of the most vulnerable banks in the EU - along with Banca Monte dei Paschi di Siena (MPS), AIB and Ulster Bank's parent RBS. All the banks clients, retail, SME and corporates are unsecured creditors of the bank and exposed to the new bail-in regime.
Irish_banks_stress_tests
The robber baron list

Only larger customers will be affected by the charge for now. The bank claims that it has no plans to levy a negative interest rate on either personal or SME customers but negative interest rates seem likely as long as the ECB continues with zero percent and negative interest rates. Indeed, they are already being seen in Germany where retail clients are being charged 0.4% to hold their cash in certain banks such as Raiffeisenbank Gmund am Tegernsee.

The news came days after it emerged that FBD, one of Ireland’s largest insurance companies, have been moving cash out of Irish bank deposits and into bonds. Fiona Muldoon, the FBD CEO cited extremely low returns on deposits and bail-ins as the reason they were withdrawing cash from Irish banks and diversifying into corporate and sovereign bonds. Muldoon said as reported by the Irish Independent that
“As they mature, and as the bank bail-in rules come into play, it’s no longer the case that for corporate investors depositing at a bank is risk free,” she added.
“To be honest, the return is abysmal now. We’ve gone back to a more typical investment portfolio for an insurance company.”
“You have to be paid for the risk you take,” she added. “You might entertain the bail-in risk if you were being properly paid. But if you’ve a bank trying to charge you for leaving your money with them, you’re not inclined to take any risk at all.”
The monetary policies being pursued by the ECB and other central banks is making deposits, banks and the banking system vulnerable. Central bank policies are contributing to individuals and companies withdrawing deposits from banks which is making already fragile banks even more fragile.

It is important to note that while there are "deposit guarantees" in place in most jurisdictions in the EU, these guarantees are only as good as the solvency of the nation providing them. Many nations in the EU remain insolvent or at least border line insolvent. Thus, the deposit guarantee level of €100,000 in many EU states and £75,000 in the UK is likely to be arbitrarily reduced to lower levels in the event of deposit "haircuts" in the next banking and financial crisis.

Prudent retail, SME and corporate clients are realizing the increasing risks facing their deposits. They can no longer afford to simply leave their deposits in a single bank account or indeed even in a few bank accounts. Diversification into other assets, including an allocation to physical gold, is becoming an important way to hedge the risks posed by negative interest rates and bail-ins.

 http://www.zerohedge.com/news/2016-08-22/irelands-biggest-bank-charging-depositors-negative-interest-rate-madness